

If You Already Have a Youth Leap Account, Is It Better to Switch to the Youth Future Savings Plan in 2 Round?
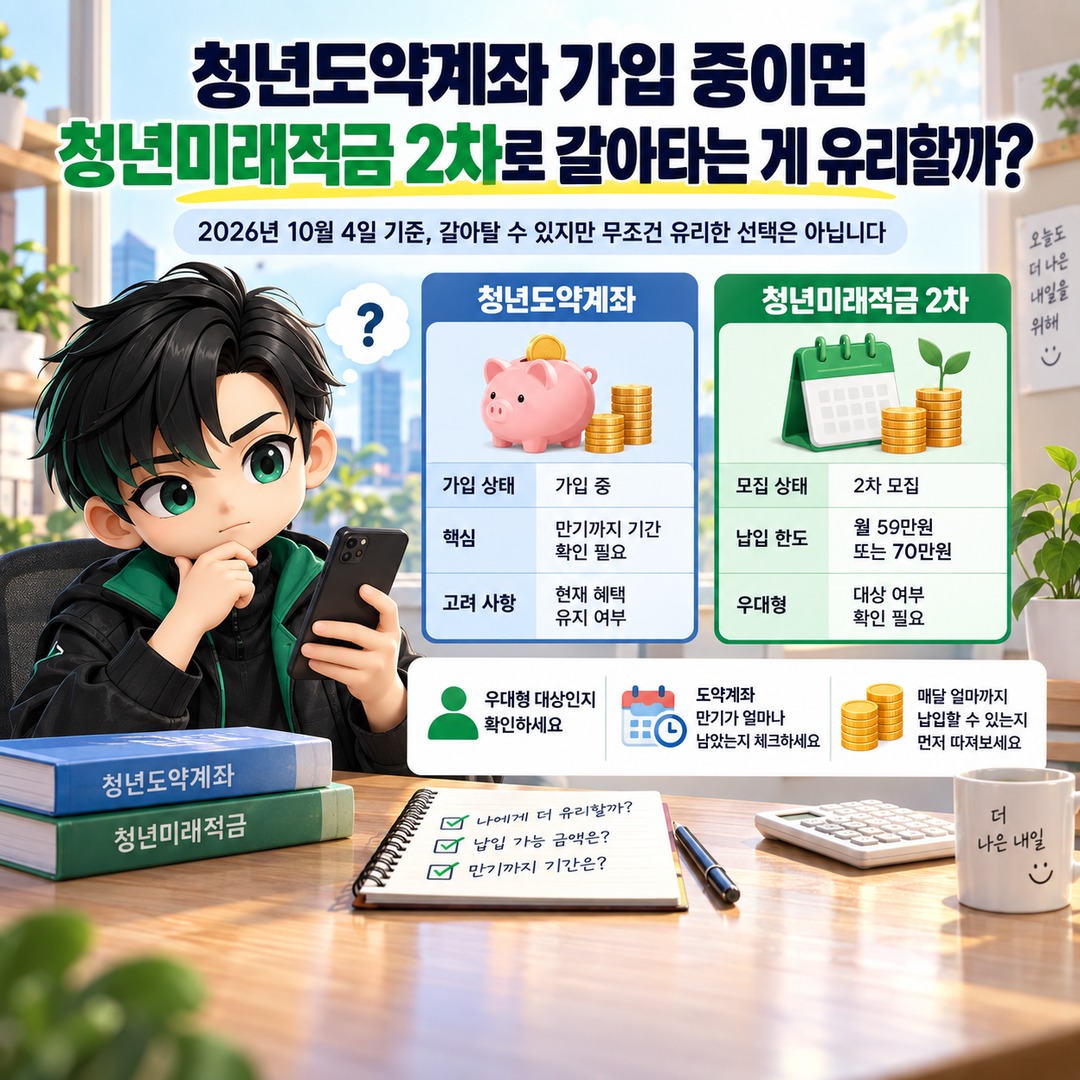
As of 2026-10-04, Youth Leap Account holders can switch to the Youth Future Savings Plan through its 2 recruitment round. However, switching is not necessarily the best choice for everyone. You need to consider whether you qualify for the preferential Youth Future Savings Plan, how much time remains until your Youth Leap Account matures, and how much you can realistically contribute each month under the KRW 500,000 and KRW 700,000 limits.
In particular, this switching process differs from simply closing your Youth Leap Account early. If you follow the designated procedure and apply for a special early termination specifically to join the Youth Future Savings Plan, you can retain the government contributions and income tax exemption on interest associated with the money you have already deposited into your Youth Leap Account.
First, Check Whether You Qualify for the Standard or Preferential Youth Future Savings Plan
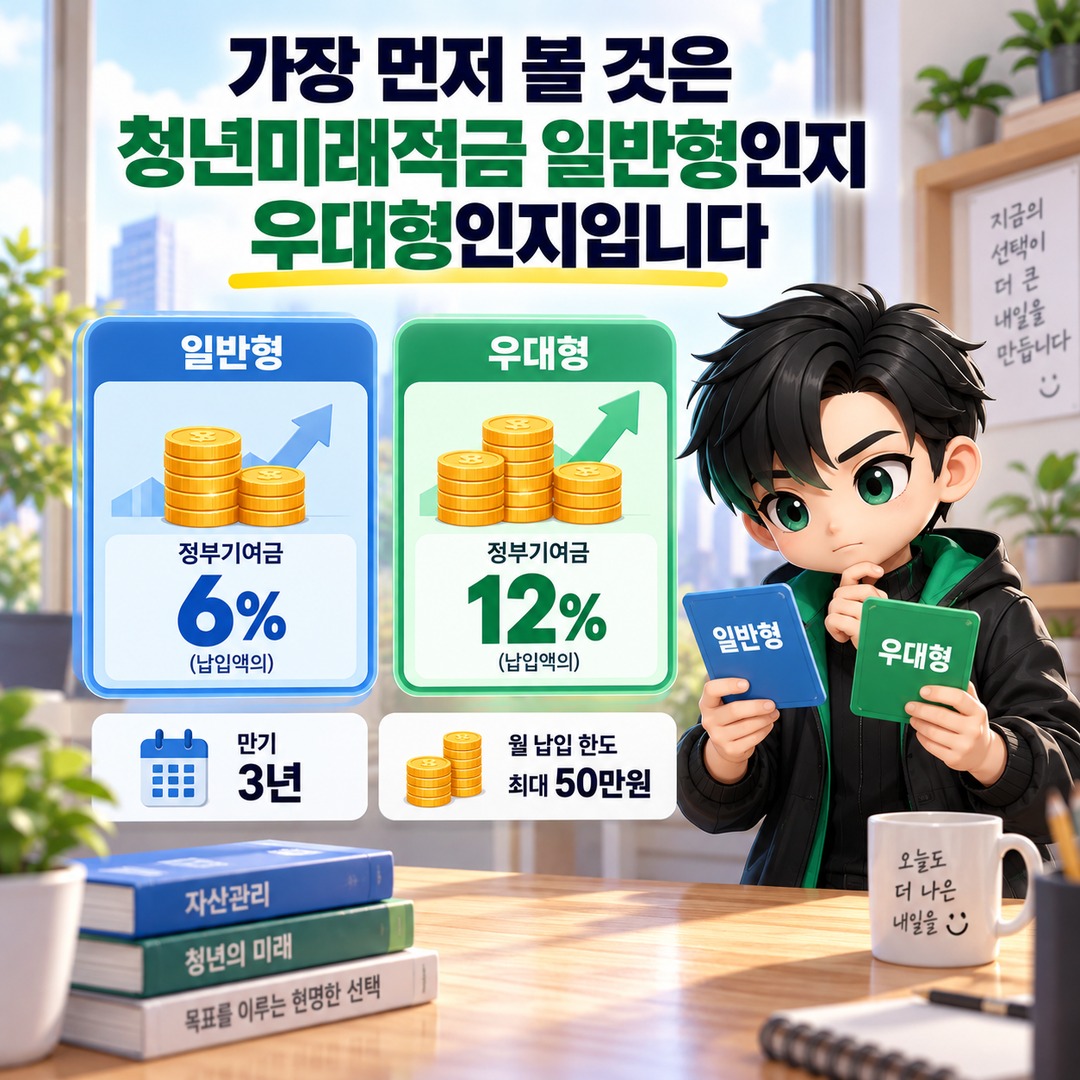
The Youth Future Savings Plan has a maturity period of 3 years and allows flexible monthly contributions of up to KRW 500,000. Government contributions amount to 6% of deposits under the standard plan and 12% under the preferential plan.
The Youth Leap Account allows monthly contributions of up to KRW 700,000, has a subscription period of 5 years, and provides government contributions at rates ranging from 3 to 6% depending on income bracket.
A straightforward comparison of the currently announced product terms reveals some substantial differences.
| Category | Youth Future Savings Plan | Youth Leap Account |
|---|---|---|
| Subscription period | 3 years | 5 years |
| Maximum monthly contribution | KRW 500,000 | KRW 700,000 |
| Government contributions | Standard: 6%; Preferential: 12% | 3–6% depending on income bracket |
| Highest interest rate | 7–8% annually, varying by financial institution | Depends on applicable conditions |
| Maximum annualized return equivalent | Approximately 14.4% for the standard plan and 19.4% for the preferential plan | Approximately 9.2% |
Therefore, if you qualify for the preferential Youth Future Savings Plan, there is a particularly strong reason to compare the benefits of switching. The standard plan also has a higher maximum annualized return equivalent than the Youth Leap Account in the official comparison. However, you still need to check the interest rate that would actually apply to you and whether you meet the requirements for preferential interest rates.
The maximum annualized return equivalents mentioned here are figures calculated by incorporating government contributions and tax exemptions and comparing the results with a simple-interest savings product. They do not mean that banks actually offer annual interest rates of 14.4% or 19.4%.
Switching Does Not Mean Giving Up the Benefits You Have Already Earned Through Your Youth Leap Account
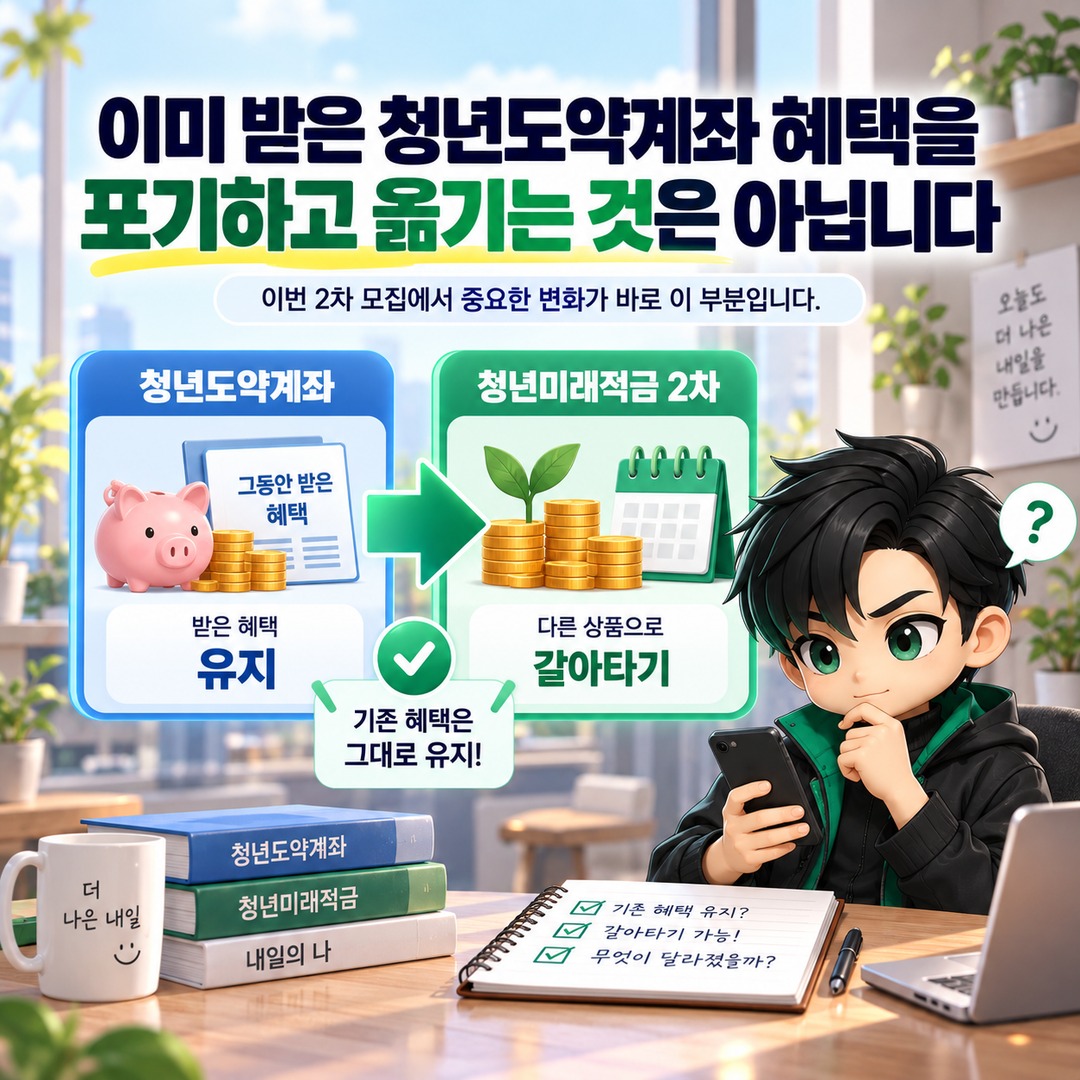
This is one of the most important changes in the 2 recruitment round.
If you use the special early termination procedure for the purpose of joining the Youth Future Savings Plan, you can retain the government contributions and income tax exemption on interest associated with the amounts already deposited into your Youth Leap Account. Preferential interest rate requirements that you have already met, or partially fulfilled, may also be recognized during the special early termination process.
Therefore, you should not treat this procedure as equivalent to terminating your Youth Leap Account through the ordinary early withdrawal process and then opening a new savings account.
Conversely, you must not close your Youth Leap Account first.
The correct sequence is: Apply for the Youth Future Savings Plan → Pass the eligibility screening → Open a Youth Future Savings Plan account → Complete the special early termination of your Youth Leap Account → Begin contributing to the Youth Future Savings Plan.
How Much Time Remains Until Your Youth Leap Account Matures Also Matters
This is the biggest reason why it is difficult to decide whether to switch based solely on the maximum returns advertised for each product.
The Youth Leap Account is a 5-year product, while the Youth Future Savings Plan requires you to begin a new 3-year contribution period from the time you switch. As a result, the length of time your money will remain committed depends on when you originally opened your Youth Leap Account.
For example, if your Youth Leap Account is approaching maturity, keeping the existing account until maturity and starting a new 3-year Youth Future Savings Plan involve different time commitments.
Conversely, if your Youth Leap Account still has a long time remaining, you qualify for the preferential Youth Future Savings Plan, and you can maintain the new plan until its 3-year maturity, switching becomes relatively more attractive.
Therefore, rather than focusing on how much you have deposited in the past, it is more accurate to compare how much you would contribute to each product from today onward and when you would be able to receive the money.
If You Have Been Consistently Contributing KRW 700,000 Each Month, Compare the Total Savings Amount Too
The maximum monthly contribution to the Youth Future Savings Plan is KRW 500,000. If you contribute KRW 500,000 every month for 36 months, your total principal contributions will amount to KRW 18,000,000.
Because the Youth Leap Account allows monthly contributions of up to KRW 700,000, comparing only the government contribution rates could cause you to overlook differences in the actual amount you can save.
If you can comfortably continue contributing KRW 700,000 per month to your Youth Leap Account and your priority is accumulating a larger lump sum, you do not necessarily need to switch simply because another product offers a higher government contribution rate.
Conversely, if contributing KRW 700,000 each month is financially burdensome and you prefer the relatively shorter 3-year period, the Youth Future Savings Plan may be a better fit.
Applications for 2 Round Begin on October 7
The application period for the Youth Future Savings Plan's 2 recruitment round runs from 2026-10-07 through October 16.
On October 7, applicants whose birth years end in an odd digit may apply. On October 8, applicants whose birth years end in an even digit may apply. From October 12 through 16, applications are open regardless of birth year.
Applicants who pass the screening can open their accounts from November 16 through 27.
Eligibility generally covers young people aged 19–34. For this recruitment round, people born from 1991-11-17 through 2007-11-27 are eligible. Up to 6 years of military service may be excluded when calculating age.
Income screening will be based on income earned in 2025. Applicants must have gross employment income of KRW 75,000,000 or less, or be small business owners with annual sales of KRW 300,000,000 or less, while also meeting household income requirements and other eligibility conditions.
Do Not Close Your Youth Leap Account First If You Want to Switch
Anyone planning to switch during the 2 recruitment round must follow the sequence below.
1. Apply for the Youth Future Savings Plan during October 7–16.
2. Wait for the results of the eligibility and income screening.
3. Once you receive confirmation of eligibility, open your Youth Future Savings Plan account during November 16–27.
4. Apply for the 'special early termination for the purpose of joining the Youth Future Savings Plan' through your existing Youth Leap Account.
5. Once the special early termination has been processed, begin contributing to the Youth Future Savings Plan.
If you do not complete the special early termination of your Youth Leap Account within the designated account-opening period after opening your Youth Future Savings Plan account, you will not be able to make contributions to the Youth Future Savings Plan.
You also cannot contribute to both accounts simultaneously while keeping your Youth Leap Account active.
So Who Should Consider Switching First?
If you qualify for the preferential Youth Future Savings Plan, can make consistent contributions over the next 3 years, and still have a relatively long time remaining until your Youth Leap Account matures, switching is worth comparing as a priority.
Even for applicants who qualify only for the standard plan, the Youth Future Savings Plan offers a higher maximum annualized return equivalent under the currently announced terms. However, you should compare the actual interest rates available to you and the remaining term of your Youth Leap Account.
On the other hand, if your Youth Leap Account is close to maturity, you intend to continue saving up to KRW 700,000 per month, or starting a new 3-year commitment feels burdensome, keeping your existing account is also an option worth serious consideration.
In particular, the new arrangement allows account holders to switch through special early termination while preserving the government contributions and tax exemptions associated with their existing Youth Leap Accounts. Therefore, the key question is not whether you will lose the benefits you have already earned, but which option better suits your circumstances when you compare the remaining contribution periods with the government contributions and interest rate conditions available under the new product.
Start by checking when you opened your current Youth Leap Account and how much you contribute each month. Then determine whether you qualify for the standard or preferential Youth Future Savings Plan. These details will make the comparison much easier.