

Why Could Rising Oil Prices Increase the Likelihood of a Fed Rate Hike? 3 Stages From the Strait of Hormuz Shock to the FOMC
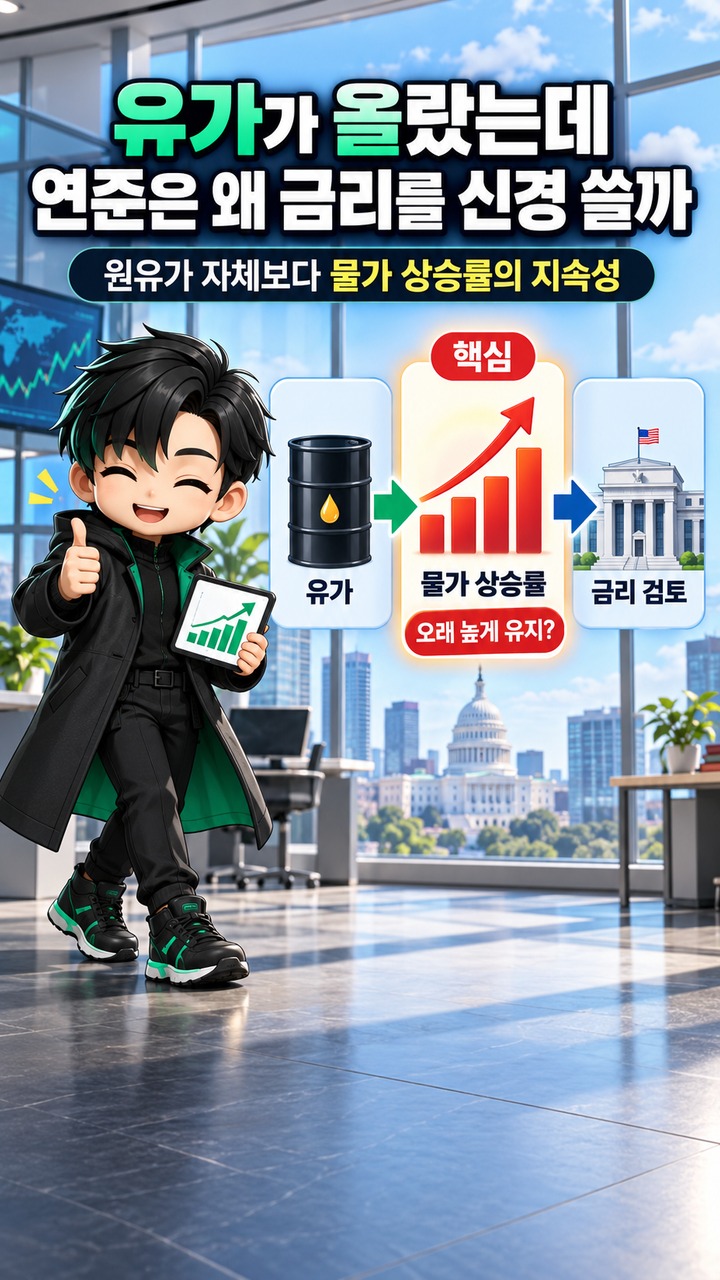
Rising oil prices do not automatically mean the Federal Reserve will raise interest rates. However, if higher oil prices spread beyond gasoline to transportation costs, production expenses, consumer prices, and inflation expectations, the Fed may consider raising rates because of the risk that inflation will remain elevated for an extended period.
This connection has become particularly important in September 2026. Amid tensions in the Middle East and concerns about supply disruptions surrounding the Strait of Hormuz, Brent crude has climbed to around 97 per barrel, and markets are once again pricing in the possibility of a rate hike at the September Federal Open Market Committee (FOMC) meeting.
Why Does the Fed Care When Oil Prices Rise?
The Fed does not raise interest rates simply to bring down crude oil prices. What matters to the central bank is how much higher oil prices push up inflation across the U.S. economy and how long that impact lasts.

An oil price shock generally passes through three stages.
| Stage | How Higher Oil Prices Spread | What the Fed Monitors |
|---|---|---|
| Stage 1 | Higher gasoline, aviation fuel, and heating costs | Headline inflation |
| Stage 2 | Higher transportation, logistics, and raw material costs | Pass-through to goods and services prices |
| Stage 3 | Expectations of persistently high inflation influence wage and pricing decisions | Inflation expectations and inflation persistence |
The first stage is relatively straightforward. When crude oil becomes more expensive, gasoline and other energy prices can rise directly.
The second and third stages are where the bigger concerns emerge.
If logistics companies pass higher fuel costs on through shipping charges and manufacturers begin passing increased production costs on to customers, even products that are not directly related to energy can become more expensive.
If businesses and consumers expect inflation to remain high and begin raising wages and selling prices in anticipation, the shock can last longer. This is precisely the kind of '2-round effect' that particularly concerns the Fed.
Why Does Oil Matter if Core Inflation Excludes Energy?
Core inflation excludes volatile food and energy prices. Therefore, a sharp one-day increase in international oil prices does not immediately produce an equally large increase in core inflation.
That does not mean the Fed ignores oil prices.
For example, if higher diesel prices increase delivery costs and those additional expenses are reflected in product prices, inflation excluding energy can also be affected.
The Federal Reserve Bank of San Francisco has also explained that when reduced crude oil supply drives prices higher, inflation and unemployment can rise simultaneously, and a central bank may choose to increase its policy rate to address inflation risks.
Therefore, the question the Fed considers is not simply "Have oil prices risen?"
The more important question is "Will the rise in oil prices remain a temporary shock, or will it spread into broader inflation across the economy?"
Why Is This Issue More Sensitive in September 2026?
The current target range for the U.S. federal funds rate is 3.50–3.75%. The Fed held rates steady at its July 28–29 FOMC meeting, but three members favored an increase of 0.25%.
With some Fed officials already favoring higher rates and energy prices rising again, markets are closely watching both oil prices and inflation indicators.
According to a Reuters report dated September 7, Brent crude climbed to approximately 97 per barrel, while markets at the time were pricing in roughly 58% probability of a U.S. rate hike at the next FOMC meeting. Because this probability changes continuously with futures prices, it should not be treated as a fixed forecast.
Fed officials are not entirely aligned in their views, either.
Fed Governor Michael Barr has left open the possibility of a rate hike if inflation fails to slow sufficiently. By contrast, Fed Governor Christopher Waller has indicated that he could support holding rates steady in September if inflation continues to moderate.
Ultimately, higher oil prices do not mean a rate hike is certain. The key question is how far rising oil prices shift the Fed's assessment of inflation risks toward tighter monetary policy.
What Should Investors Actually Watch Before the September FOMC Meeting?
The September 2026 FOMC meeting will take place on September 15–16, U.S. local time. Economic projections are also scheduled to be released alongside the meeting.
Rather than focusing solely on oil prices, it is important to monitor three factors together.
First is the direction of consumer inflation. Investors need to distinguish between energy prices pushing up headline inflation alone and a renewed acceleration in core inflation.
Second is the labor market. Even if inflation remains high, rapidly deteriorating employment conditions would make it more difficult for the Fed to raise rates. Conversely, if employment remains resilient while inflation strengthens again, the case for a rate hike could become stronger.
Third is how long oil prices remain elevated. An oil price spike that reverses within days has different monetary policy implications from a supply disruption that continues for months.
The Bank of Korea has also recently identified prolonged closure of the Strait of Hormuz, rising oil prices, and supply chain disruptions as important variables in its assessment of the U.S. policy rate outlook, particularly because higher producer prices could feed through to consumer prices.
Do U.S. Stocks Always Fall When Oil Prices Rise?
Not necessarily. The impact of higher oil prices on stocks depends on the industry and how interest rates move at the same time.
For the broader market, the transmission mechanism of higher oil prices → inflation concerns → higher interest rate expectations → rising Treasury yields may be more troubling than oil prices themselves.
When interest rates rise, the discount rate used to calculate the present value of future earnings also increases. Growth stocks whose valuations depend heavily on earnings expected far into the future can be relatively sensitive to such interest rate changes.
In fact, in early September, major government bond yields around the world rose together as higher oil prices intensified inflation concerns and expectations of interest rate increases.
Meanwhile, some energy companies may move differently because higher crude oil prices can improve their earnings outlook. Rather than reducing the relationship to a simple rule such as "higher oil prices mean falling stocks," investors should examine the connections among oil prices, inflation, policy rate expectations, and long-term government bond yields.
What Matters Most Now Is Not the Oil Price Itself, but Whether Its Effects Spread
When assessing the September FOMC meeting, there is no need to focus exclusively on whether international oil prices stand at 95 or 100.
The more important questions are how long elevated oil prices persist and how widely those costs spread into goods and services prices and inflation expectations.
If oil prices stabilize quickly and core inflation slows, pressure on the Fed to raise interest rates could ease. Conversely, if higher oil prices persist and core inflation strengthens again, the likelihood of a rate hike could increase.
The key issue investors should monitor ahead of the September 2026 15–16 FOMC meeting is ultimately not oil prices alone, but whether the chain of 'oil prices → inflation → interest rates' is actually taking shape. Interest rate expectations and market prices can change frequently in response to new economic data and geopolitical developments, and no particular direction of stock price movements or investment returns is guaranteed.
※ This article is provided for informational purposes to help readers understand market developments and does not constitute a recommendation to invest in any particular stock or asset. Readers are responsible for their own final decisions and investment outcomes.