

How Much Would Your Mortgage Limit Decrease With an Annual Salary of KRW 50,000,000 and an Existing Personal Loan of KRW 30,000,000?
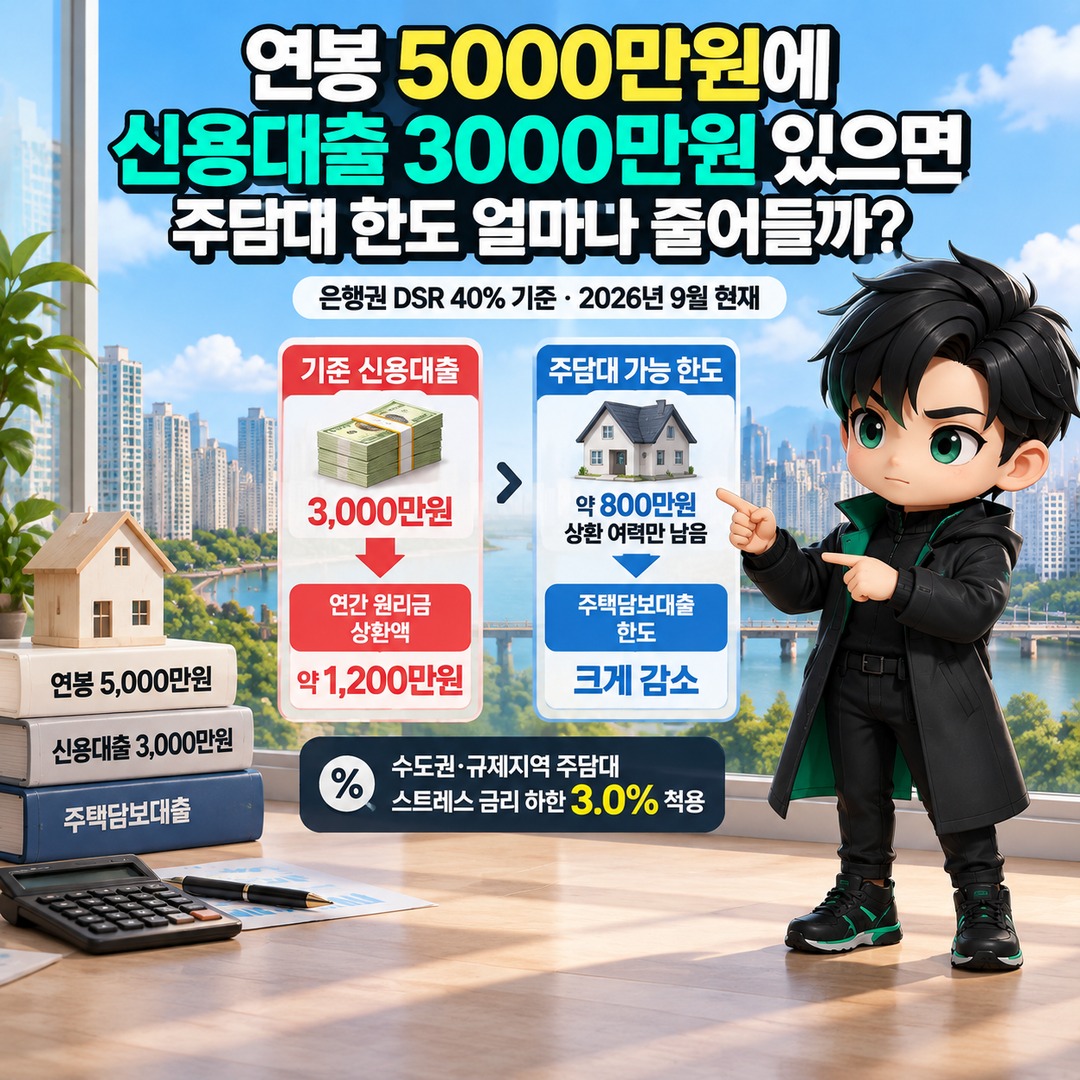
Even with an annual income of KRW 50,000,000, an existing personal loan can significantly reduce your mortgage borrowing limit. Under the banking sector's DSR limit of 40%, your annual debt repayment capacity is KRW 20,000,000, but an existing personal loan uses up part of that allowance first.
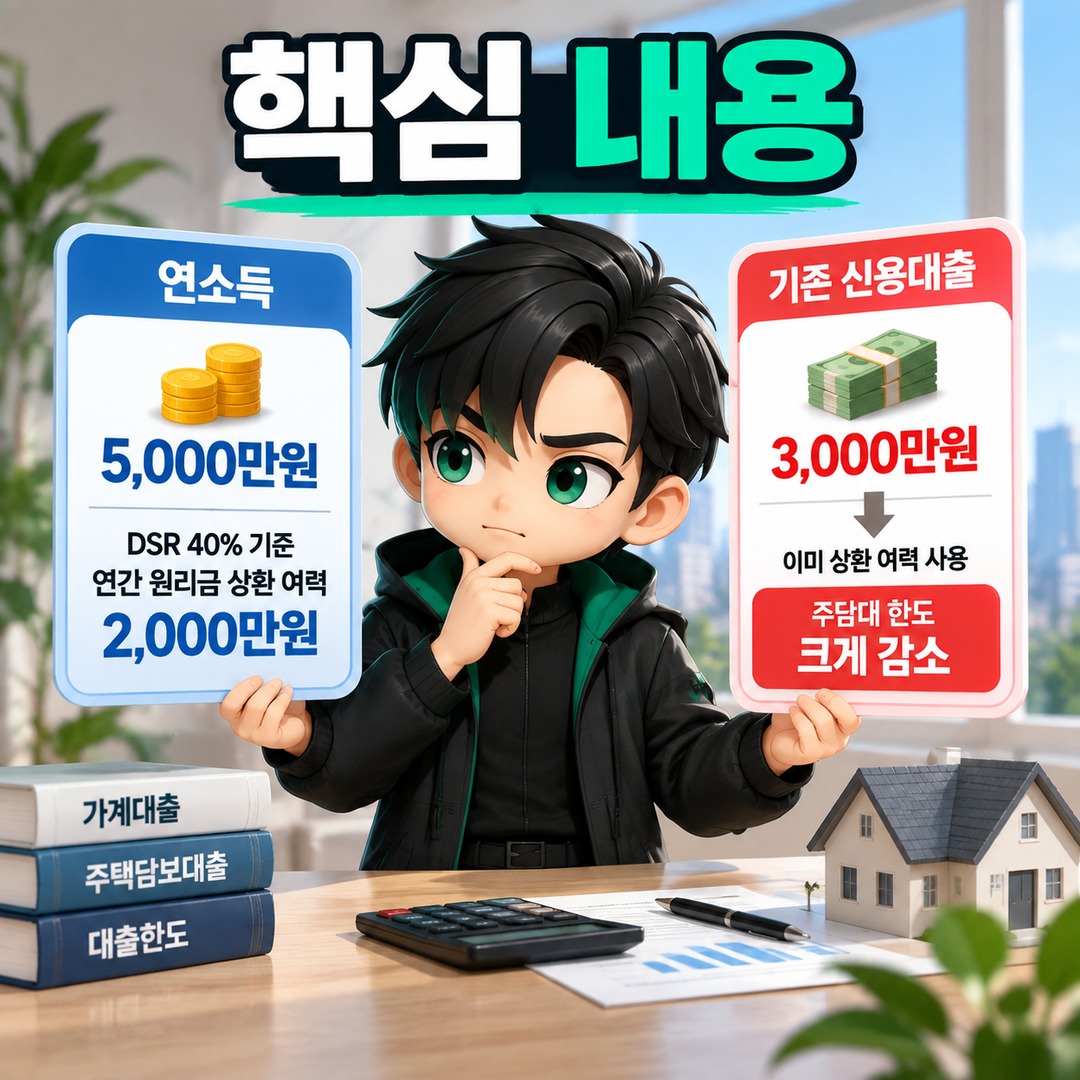
In particular, as of September 2026, the minimum stress interest rate for mortgages in the Seoul metropolitan area and regulated areas is 3.0%. This does not mean that 3% percentage points are automatically added to the interest you actually pay. Instead, it means a higher interest rate is assumed when calculating your borrowing limit.
With an Annual Salary of KRW 50,000,000, Your Annual DSR Repayment Allowance Is KRW 20,000,000
DSR does not consider only your mortgage. According to the Financial Services Commission, the debt service ratio (DSR) is calculated by dividing the annual principal and interest repayments on all household loans by annual income.
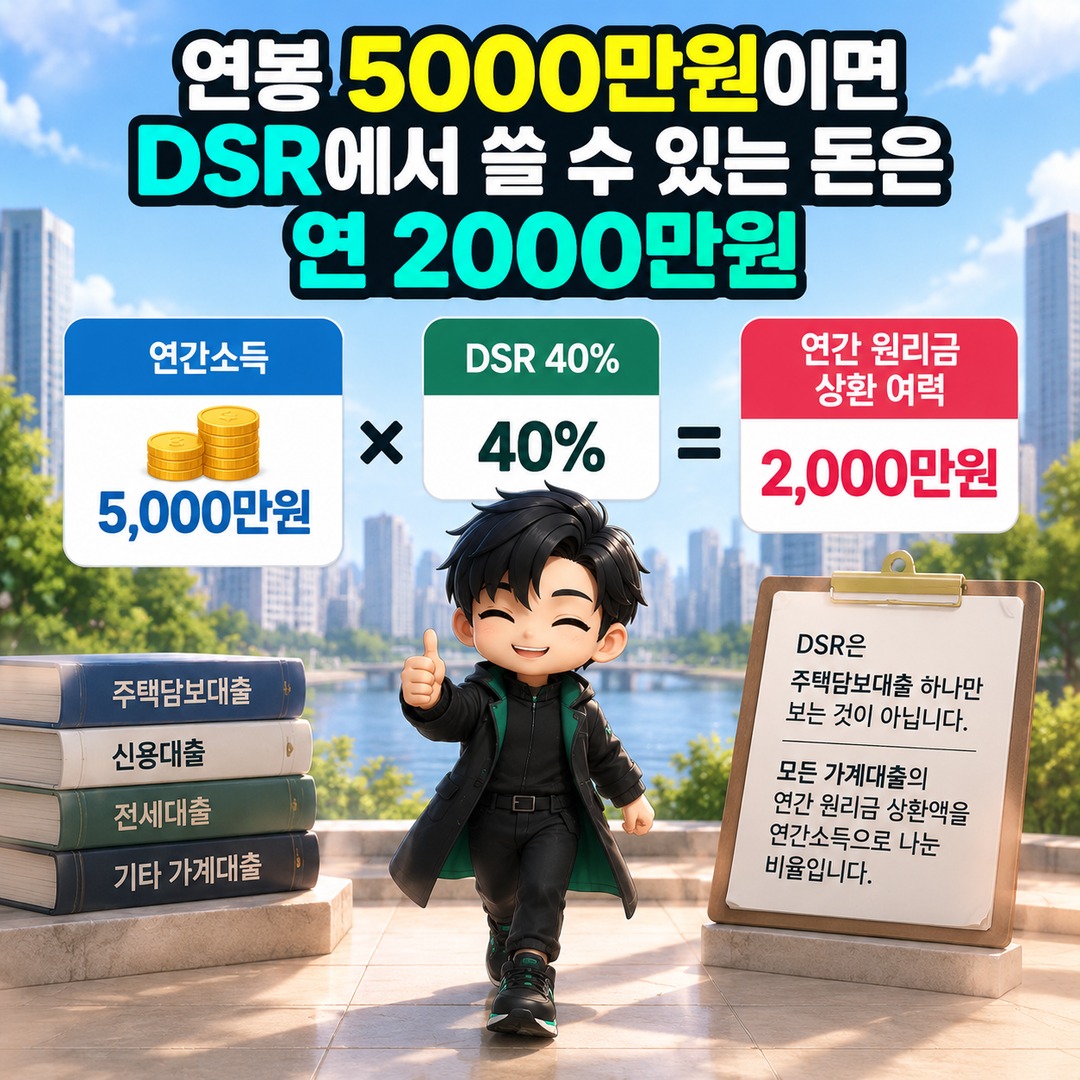
Applying the banking sector's DSR limit of 40% in a simplified calculation gives the following result.
KRW 50,000,000 × 40% = KRW 20,000,000 per year
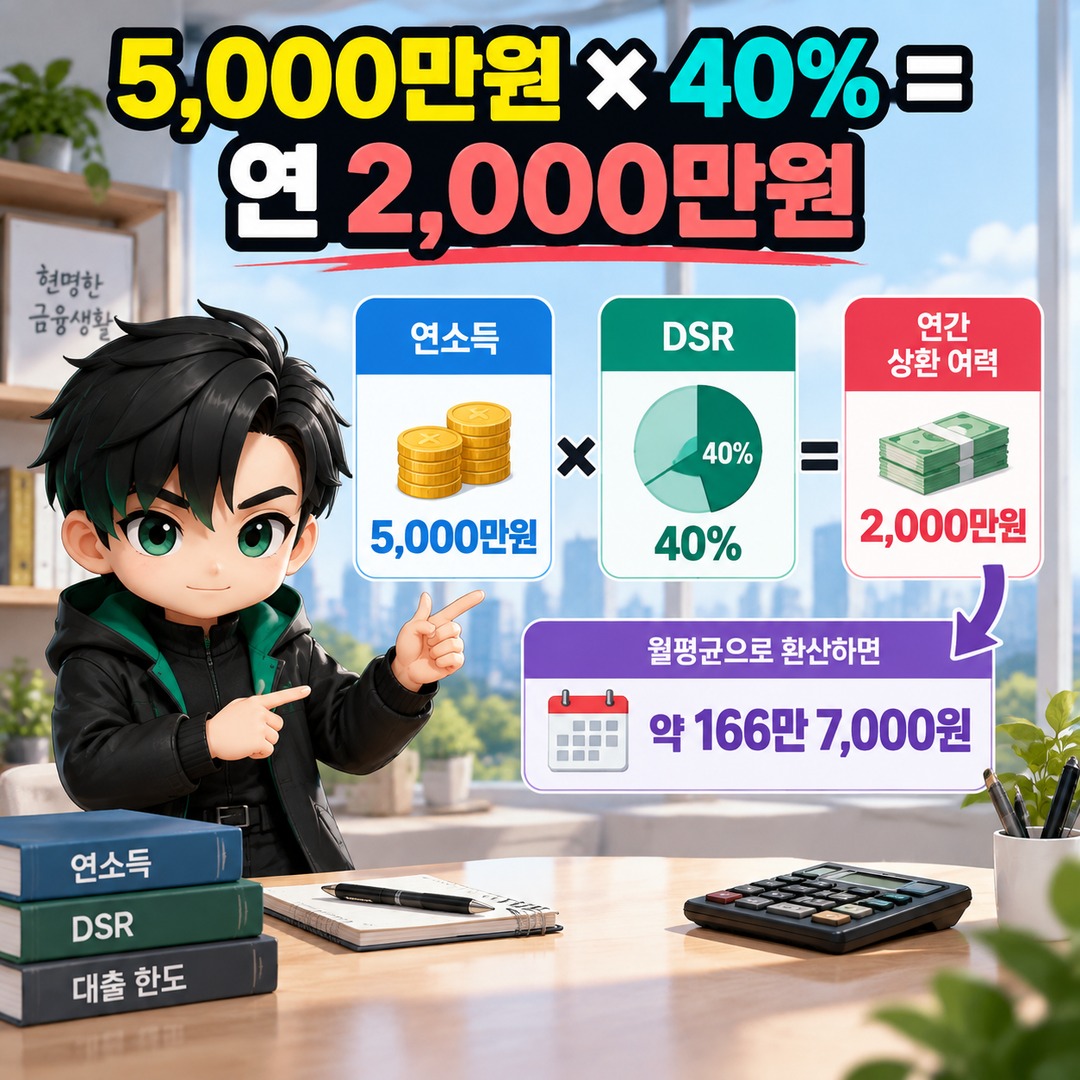
Converted into a monthly average, this is approximately KRW 1,667,000.
The important point is that someone can use the entire KRW 1,667,000 toward repayments on a new mortgage only if they have no existing loans.
If you already have debts included in DSR calculations, such as personal loans or car installment loans, you must deduct those principal and interest repayments first.
Why Does an Existing Personal Loan of KRW 30,000,000 Reduce Your Mortgage Limit More Than Expected?
You should not calculate the DSR impact of a personal loan by looking only at the interest deducted from your bank account each month.
For DSR calculations, personal loans with lump-sum repayment structures may be assigned a relatively short assumed repayment period. The Financial Services Commission previously revised the assumed DSR repayment period for personal loans to 5 years to better reflect actual conditions.
For an easy-to-understand example, consider the following assumptions.
| Item | Assumption |
|---|---|
| Annual income | KRW 50,000,000 |
| Existing personal loan | KRW 30,000,000 |
| Personal loan interest rate | 5% per year |
| Assumed personal loan repayment period | 5 years |
| Banking sector DSR | 40% |
In a simplified calculation, the annual amount attributed to repayment of the personal loan principal is:
KRW 30,000,000 ÷ 5 years = KRW 6,000,000
Applying annual interest of 5% in a simplified calculation adds approximately KRW 1,500,000.
Therefore, in this example, the existing personal loan accounts for approximately KRW 7,500,000 in annual principal and interest repayments.
If the total DSR repayment allowance for a borrower earning KRW 50,000,000 annually is KRW 20,000,000, the remaining annual repayment capacity for a new mortgage would be approximately KRW 12,500,000.
KRW 20,000,000 - KRW 7,500,000 = KRW 12,500,000
This is the author's calculation for illustrative purposes. Actual DSR calculations may vary depending on the loan's repayment method, remaining term, interest rate, product conditions, and other factors.
Example: Mortgage Borrowing Capacity Falls From KRW 250,000,000 to Approximately KRW 157,000,000
Let's compare the difference using the same assumptions.
Assume a new mortgage in the Seoul metropolitan area or a regulated area carries an annual interest rate of 4%, with an additional stress interest rate of 3% percentage points. The interest rate used for the DSR assessment would then be approximately 7% per year. The minimum mortgage stress interest rate of 3.0% for the Seoul metropolitan area and regulated areas remains applicable in 2026.
Using a simplified calculation based on equal monthly principal and interest payments over 30 years gives the following results.
| Existing personal loan | Annual principal and interest repayment capacity available for the mortgage | Example mortgage calculation |
|---|---|---|
| None | KRW 20,000,000 | Approximately KRW 250,500,000 |
| KRW 30,000,000, assuming annual interest of 5% | Approximately KRW 12,500,000 | Approximately KRW 156,600,000 |
The Difference Is Approximately KRW 93,900,000.
The author's calculation is based on `annual income KRW 50,000,000 · bank DSR 40% · mortgage assessment interest rate 7% · equal principal and interest repayments over 30 years · personal loan KRW 30,000,000 at annual interest of 5% · assumed personal loan repayment period of 5 years`.
In other words, having an outstanding personal loan balance of KRW 30,000,000 does not mean your mortgage limit decreases by exactly KRW 30,000,000.
In this example, an existing personal loan of approximately KRW 30,000,000 reduces the calculated amount available for a new mortgage by approximately KRW 94,000,000. This is because the period over which personal loan principal is allocated in DSR calculations can be shorter than for mortgages, resulting in a relatively large annual principal and interest repayment burden.
These figures do not represent actual bank underwriting results.
Aren't Personal Loans of KRW 100,000,000 or Less Excluded From Stress DSR?
This is one of the most commonly misunderstood points.
Having an Outstanding Personal Loan Balance of KRW 100,000,000 or Less Does Not Mean the Existing Loan Is Excluded From Mortgage DSR Calculations.
The Financial Services Commission's threshold of 'outstanding personal loan balances exceeding KRW 100,000,000' determines when an additional stress interest rate is applied to personal loans. Under the 3-stage stress DSR framework, the stress interest rate is also applied to personal loans when their total outstanding balance exceeds KRW 100,000,000.
Therefore, someone with an existing personal loan of KRW 30,000,000 who is considering a new mortgage could find a substantial difference between their estimated and actual borrowing limits if they assume, "It's below KRW 100,000,000, so I don't need to worry about the personal loan."
Check Your Overdraft Credit Line Before Consulting a Mortgage Lender
If you have an overdraft credit line, it is best not to judge its impact solely by the amount you have actually used.
When considering a mortgage, you should first check how existing household loans, including ordinary personal loans and overdraft credit lines, are reflected in DSR calculations. This is because DSR fundamentally measures the combined principal and interest repayment burden of multiple household loans rather than assessing a mortgage in isolation.
In particular, if you have an overdraft credit line that has been opened but not used, it is more accurate to establish your housing budget after confirming with the bank how that credit line affects your DSR.
If You Pass the DSR Assessment, Can You Borrow the Entire Calculated Amount?
Not necessarily.
DSR is only one of several restrictions that determine mortgage borrowing limits. When actually purchasing a home, other requirements also apply, including the loan-to-value ratio (LTV), collateral value, mortgage caps based on property prices, and individual financial institutions' underwriting standards.
Currently, mortgages for home purchases in the Seoul metropolitan area and regulated areas are also subject to different maximum limits depending on the property's market value.
| Property market value | Maximum mortgage limit for home purchases |
|---|---|
| KRW 1,500,000,000 or less | KRW 600,000,000 |
| Above KRW 1,500,000,000 and up to KRW 2,500,000,000 | KRW 400,000,000 |
| Above KRW 2,500,000,000 | KRW 200,000,000 |
The Financial Services Commission began applying these differentiated limits on 2025-10-16.
Therefore, the amount you can actually borrow may often be determined by whichever applicable limit is lower, whether that is the DSR-based limit or restrictions such as LTV and property-price-based lending caps.
Why You Should Calculate Your Existing Debt Before Looking at Homes
Estimating how expensive a home you can afford based solely on your annual salary can easily lead to inaccurate results.
If your annual income is KRW 50,000,000, you should first use the annual principal and interest repayment allowance of KRW 20,000,000 under the banking sector's DSR limit of 40% as your starting point. Then check how much of that allowance is already used by debts included in DSR calculations, such as existing personal loans and car installment loans.
Next, account for the interest rate type and term of the new mortgage, along with the stress interest rate applicable in the Seoul metropolitan area and regulated areas. Finally, check the LTV requirements and maximum mortgage limits based on property prices. Following this sequence produces a more realistic estimate.
This explains why two people earning the same annual salary of KRW 50,000,000 can have significantly different mortgage borrowing limits if one has no existing loans while the other has an outstanding personal loan.
※ This is a general explanation based on the rules in effect as of 2026-09-26. Actual borrowing limits and DSR calculations may vary depending on how income is recognized, the types of existing debt, repayment methods, property location and price, interest rate structure, and financial institutions' underwriting standards. Confirm the applicable terms with your lender before signing a contract.
※ This article is provided for reference to help readers understand market conditions and does not constitute an investment recommendation for any particular security or asset. You are responsible for your own final decisions and investment outcomes.
Related Articles
Does the iPhone Duo Really Have No Support for Physical SIM Cards?