

Why Your National Pension Deduction Differs from Your Salary × 4.75%: How Standard Monthly Income Is Determined
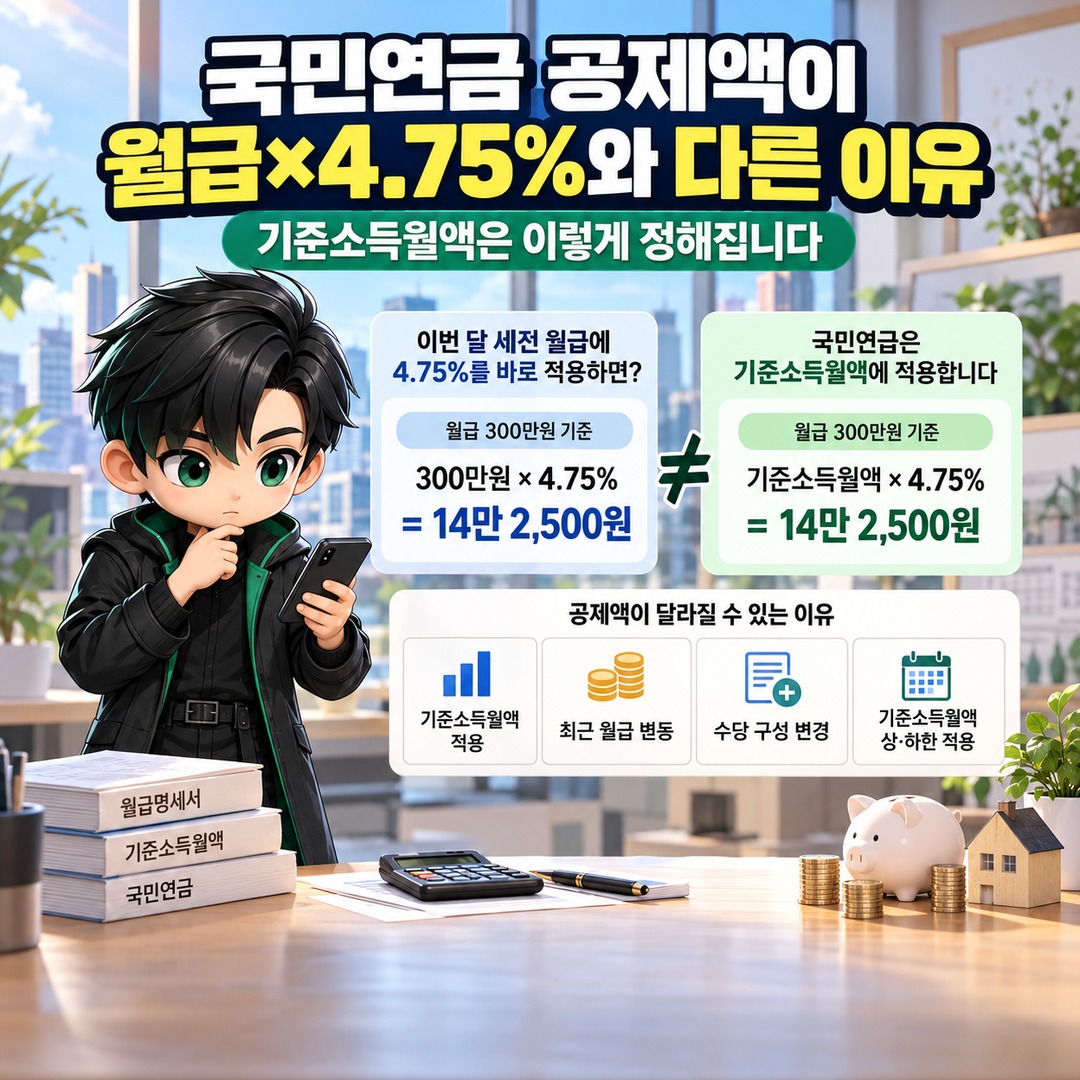
In 2026, the employee contribution rate for workplace subscribers to the National Pension is 4.75%, but this does not mean that 4.75% is automatically multiplied by this month's gross salary to calculate the deduction. National Pension contributions are calculated by applying the contribution rate to the 'standard monthly income.' If your salary has recently increased or the composition of your allowances has changed, the National Pension deduction on your payslip may differ from a simple calculation.
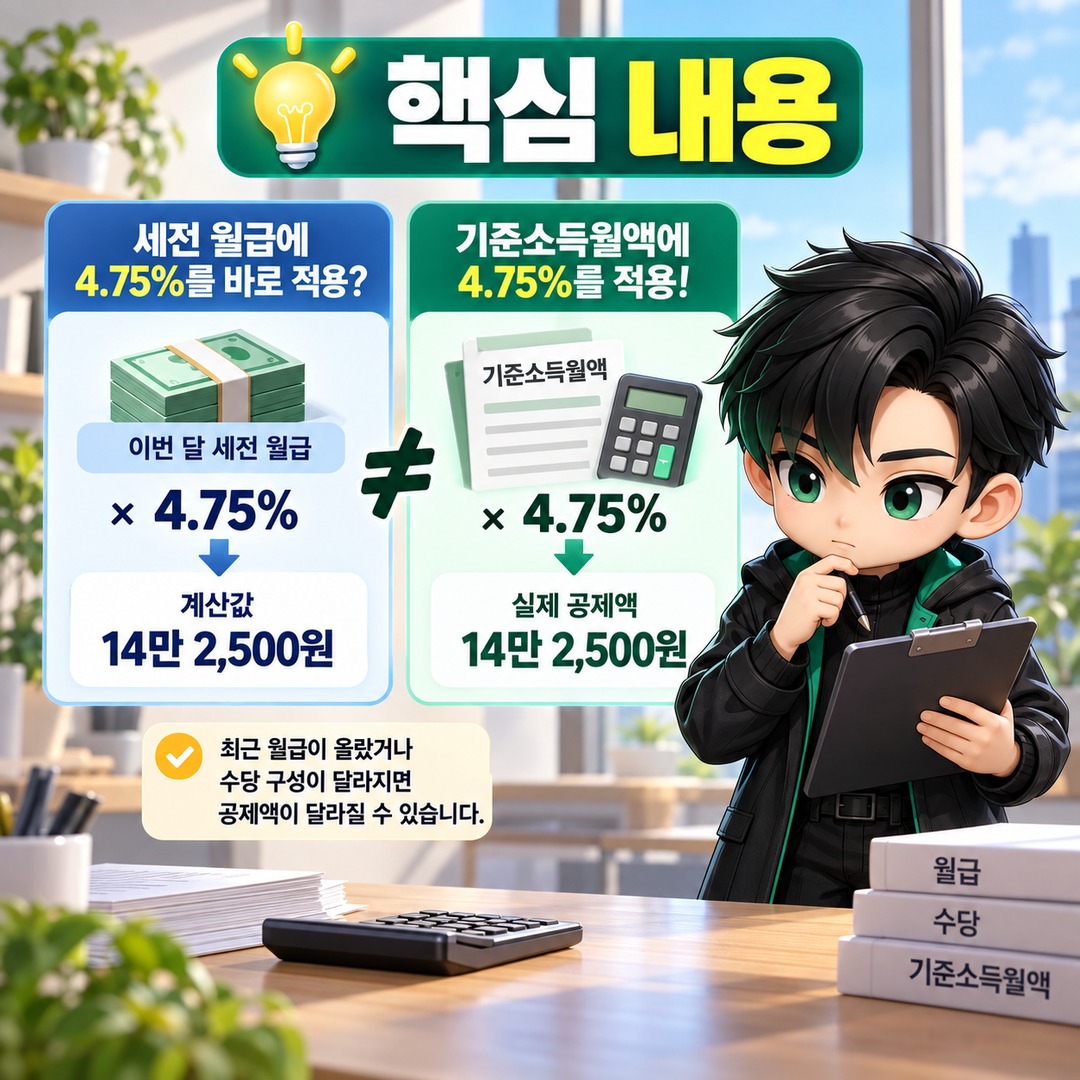
The calculation showing an employee contribution of KRW 142,500 for a monthly salary of KRW 3,000,000 is also accurate only when the standard monthly income is KRW 3,000,000. So why might a different amount appear on your payslip?
National Pension Contributions Are Based on Standard Monthly Income, Not Simply This Month's Salary
The formula for calculating National Pension contributions is straightforward.
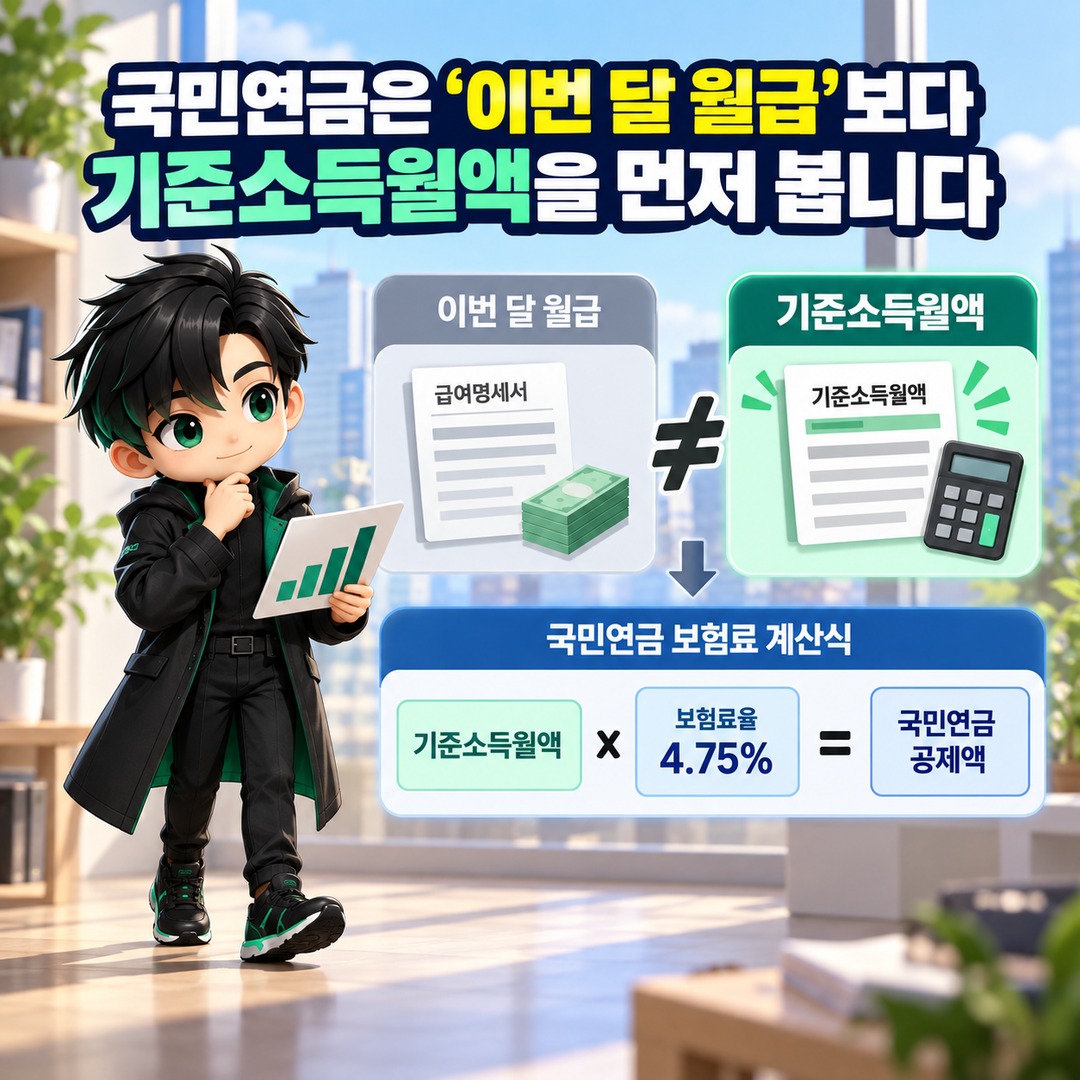
Standard Monthly Income × Contribution Rate = National Pension Contribution
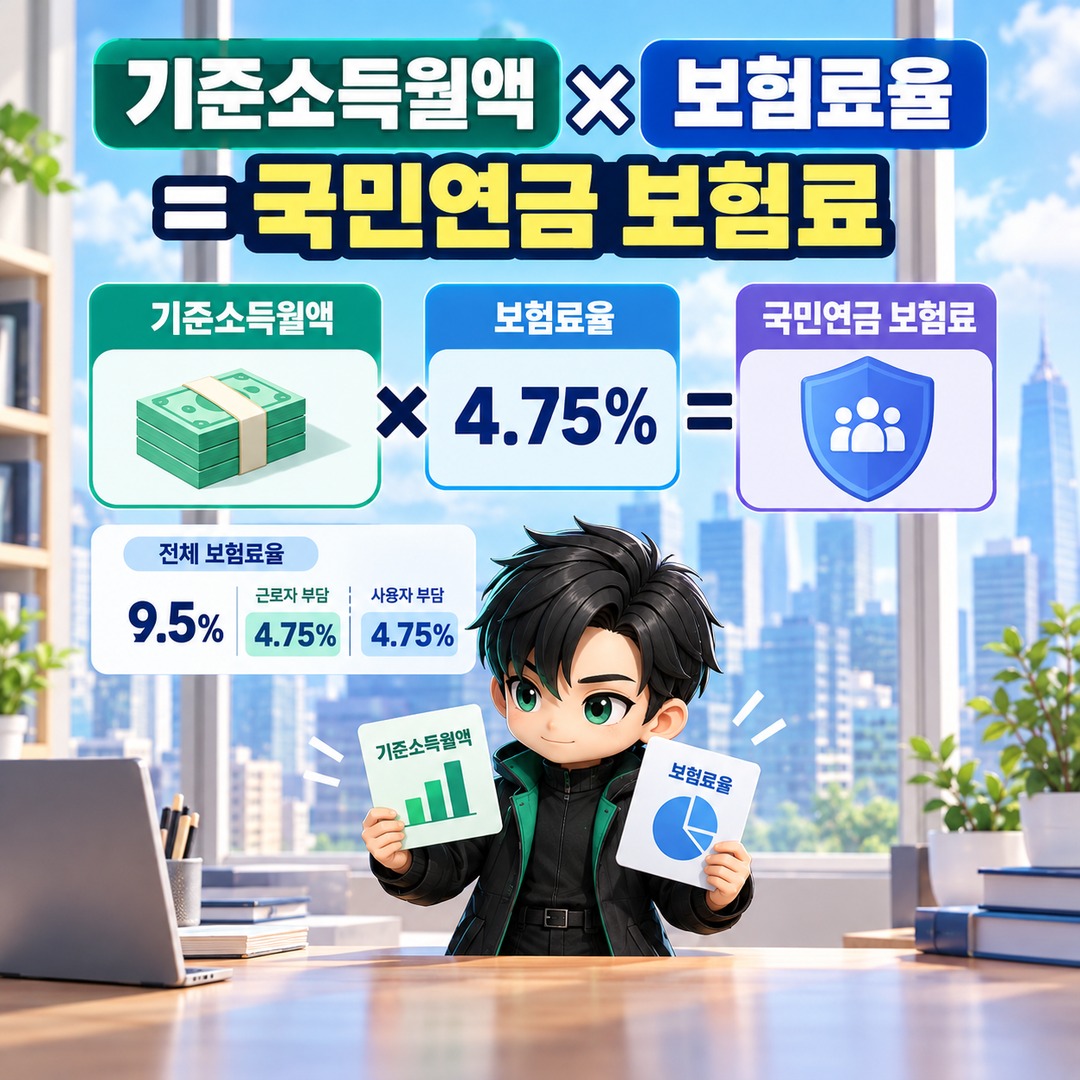
In 2026, the total contribution rate for workplace subscribers is 9.5%, with employees and employers each paying 4.75%. Therefore, the basic formula for the amount actually deducted from an employee's salary is standard monthly income × 4.75%.
The key term here is 'standard monthly income.'
Standard monthly income is the income basis established for calculating National Pension contributions and pension benefits. From 2026-07-01 through 2027-06-30, it is determined within a range from a minimum of KRW 410,000 to a maximum of KRW 6,590,000.
| Standard Monthly Income | Employee Contribution at 4.75% |
|---|---|
| KRW 2,500,000 | KRW 118,750 |
| KRW 3,000,000 | KRW 142,500 |
| KRW 4,000,000 | KRW 190,000 |
| KRW 6,590,000 | KRW 313,025 |
The amounts above are simplified calculations for typical workplace subscribers who do not receive subsidies or other financial support.
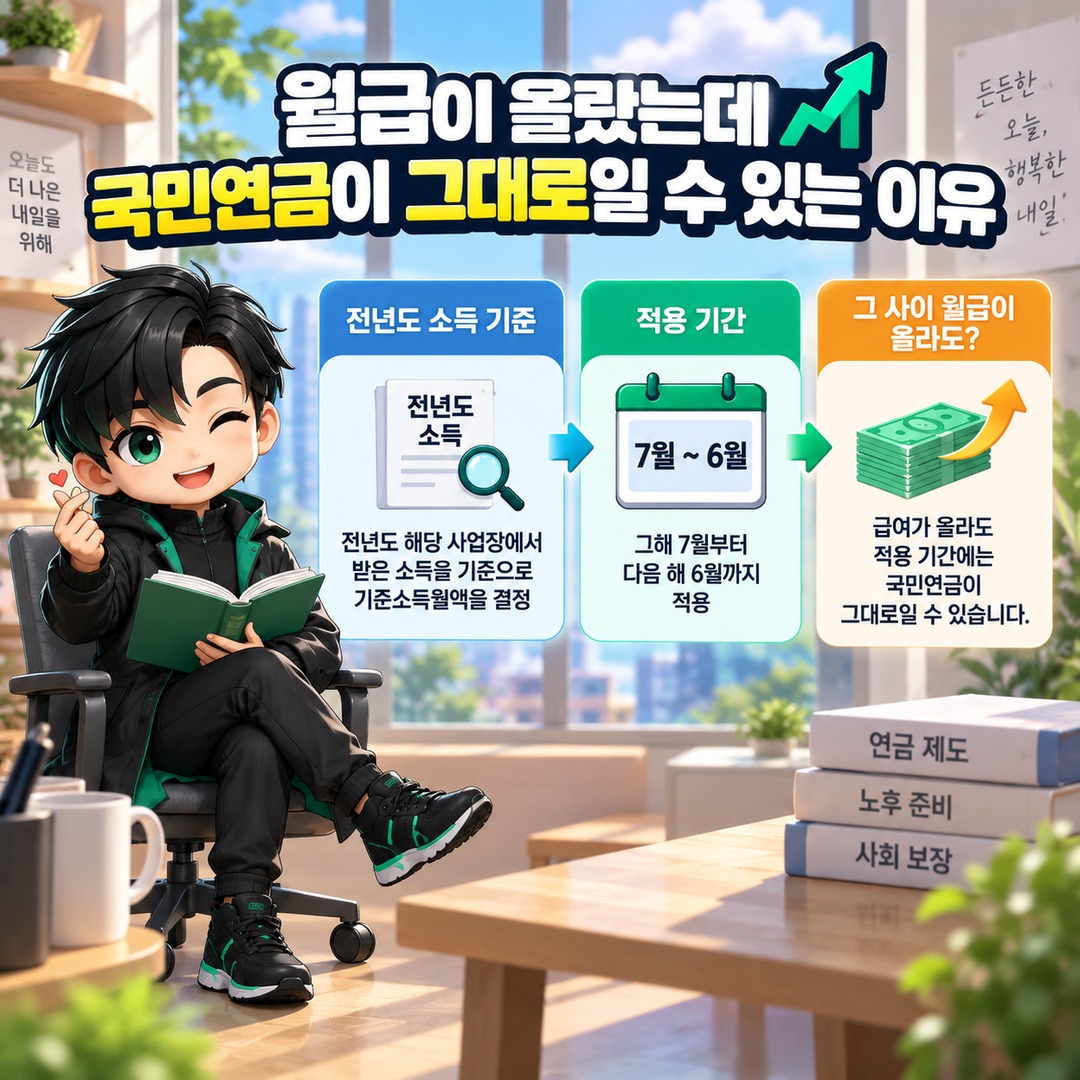
Why Your National Pension Deduction May Stay the Same Even After a Salary Increase
For employees who remain with the same employer, standard monthly income is generally recalculated based on income received from that workplace during the previous year and applied from July of the current year through June of the following year.
The National Pension Service determines standard monthly income by dividing the previous year's total income by the total number of days in the employment period and then multiplying the result by 30.
For example, suppose your standard monthly income was set at KRW 3,000,000 in July 2026, but your monthly salary subsequently increased to KRW 3,300,000.
If you calculate the contribution based only on your current salary:
KRW 3,300,000 × 4.75% = KRW 156,750
However, if the standard monthly income currently applied to your National Pension contributions is still KRW 3,000,000:
KRW 3,000,000 × 4.75% = KRW 142,500
The difference between these two amounts is KRW 14,250 per month. This is the author's calculation, and the actual amount on your payslip should be checked against your individual standard monthly income and the information reported by your employer.
Therefore, if your National Pension deduction does not immediately increase in proportion to a salary raise, that does not necessarily mean there has been a calculation error.
The Calculation Basis Is Different for Recently Hired Employees
New employees or those returning to work may not have income records from the previous year at their current workplace.
In such cases, the employer reports standard monthly income based on the amount it has agreed to pay the employee. According to National Pension Service guidelines, this determination also includes employment income that can reasonably be expected at the time of hiring or returning to work.
As a result, even employees at the same company receiving the same monthly salary may need to follow different verification procedures depending on when they joined the company or the standard monthly income previously determined for them.
If the National Pension deduction on your payslip differs from what you expected, the quickest approach is to check the standard monthly income reported for you by your employer, rather than simply recalculating 'gross monthly salary × 4.75%.'
Tax-Exempt Income Can Create a Difference Between Total Pay and the Contribution Basis
For National Pension purposes, an employee's income is not always identical to the sum of every payment listed on the payslip.
The National Pension workplace administration guidelines explain that the relevant income is wages paid to employees in return for their work, excluding employment income classified as tax-exempt under the Income Tax Act. Therefore, if your salary includes tax-exempt items, the National Pension calculation basis may differ from your total gross pay.
However, whether a particular allowance actually qualifies as tax-exempt should not be determined solely by its name. Checking both your payslip and your employer's reported information is the most accurate approach.
If Your Monthly Salary Exceeds KRW 6,590,000, 4.75% Is Not Applied Indefinitely
As of September 2026, the applicable upper limit for standard monthly income is KRW 6,590,000. The application period runs from 2026-07-01 through 2027-06-30.
Therefore, even if the income used as the basis exceeds the upper limit, only up to KRW 6,590,000 is reflected in the National Pension contribution calculation.
KRW 6,590,000 × 4.75% = KRW 313,025
In other words, when making a simplified calculation for a typical employee subscribed through a single workplace, the monthly employee contribution calculated using the standard monthly income ceiling is KRW 313,025.
Even if your monthly salary rises to KRW 7,000,000 or KRW 8,000,000, your National Pension contribution does not continue increasing according to the formula 'current monthly salary × 4.75%.'
Conversely, the lower limit for standard monthly income applicable from July 2026 is KRW 410,000. The National Pension Service explains that if the reported monthly income falls below the lower limit, the lower limit is applied as standard monthly income, while income above the upper limit is subject to the upper limit.
If Your Income Changes Significantly, Must You Wait Until the Next Regular Recalculation?
Not necessarily.
If a workplace subscriber's actual income increases or decreases by 20% or more compared with their current standard monthly income, a special provision allows an application to change the standard monthly income, provided the relevant requirements are met. The employer submits the change application with supporting documents after obtaining the employee's consent.
In principle, the revised standard monthly income takes effect from the month following the application and is not applied retroactively. A subsequent adjustment may also be made using tax records and other information.
It is important to distinguish minor wage fluctuations from actual income changes of 20% or more.
What to Check When Your National Pension Deduction Looks Incorrect
First, check the National Pension deduction shown on your payslip. The key is then to verify your National Pension standard monthly income, rather than your current salary.
For example, if your National Pension deduction is KRW 142,500, calculating backward gives:
KRW 142,500 ÷ 4.75% = KRW 3,000,000
Therefore, if there are no subsidies or other variables, you can check whether the deduction was calculated using a standard monthly income of KRW 3,000,000.
Next, determine whether the difference between your current salary and standard monthly income results from the regular recalculation based on the previous year's income, a report submitted when you joined or returned to work, or tax-exempt employment income.
As of September 2026, the standard monthly income range is KRW 410,000–KRW 6,590,000, and the employee contribution rate for workplace subscribers is 4.75%. For the most accurate information about your individual standard monthly income and subscription records, consult the National Pension Service.
Related Articles
5 Indicators Worth Using Alongside RSI: Why Moving Averages and Trading Volume Come First